For most of the past decade, satellite connectivity and mobile networks were separate worlds. Operators sold cellular service where they had towers. Satellite companies served ships, aircraft and remote sites with their own terminals and their own contracts. Enterprises that needed both had to stitch them together.
That separation is breaking down quickly. In early September 2026, AT&T Business announced it would offer Amazon Leo satellite broadband alongside its fibre and 5G services as a single managed product. A few days later, reports emerged that Europe’s largest operators were in early talks about a joint bid for EU-controlled satellite spectrum. In the background, Amazon is working towards a second satellite system designed to connect phones and other cellular devices directly.
For IoT operators, fleet owners and anyone managing assets in places where coverage runs out, these moves raise a practical question: which satellite options will be available through the providers they already use, and when?
What AT&T And Amazon Announced
AT&T described the deal as making it the first major US operator to offer converged connectivity that combines Amazon Leo’s low Earth orbit service with fibre and 5G as one fully managed service, according to AT&T’s own announcement on 8 September 2026.
One Bill, Three Networks
The offer is built around simplicity for business customers. AT&T will provide the equipment for satellite connections, a single bill, one point of contact and round-the-clock technical support. Customers will not need to buy satellite service separately and integrate it with their terrestrial networks.
Shawn Hakl, senior vice president and head of product at AT&T Business, argued that the market’s problem is not a lack of options. “Customers have no shortage of connectivity options,” he said. “What enterprise and public sector customers need is a connectivity platform that delivers greater reliability.” He said AT&T could provide that by bringing together “fiber, 5G, and low Earth orbit satellite” in a single managed architecture.
Who It Is For
AT&T lists remote and distributed operations such as mining, oil and gas, agriculture, construction and logistics among the target users. It also names temporary deployments, including events, construction sites and emergency response, as well as transport and fleet operations that need to keep mobile assets connected. Resilience is a central theme: satellite as a backup path when fibre is cut or a terrestrial network fails.
Chris Weber, vice president of Amazon Leo business and product, said the service “builds resilience into networks and expands what’s possible for customers.”
Not Yet Available
AT&T said pricing, service details and configurations would follow in the coming months. The rollout is being phased, with an emphasis on proving business-grade reliability before broad availability. Mobile World Live noted that the timeline could stretch into 2027, partly because of delays to Amazon’s launch plans after a Blue Origin New Glenn rocket exploded during pre-launch testing in May.
What This Deal Is, And What It Is Not
It is easy to group every satellite announcement under the label of direct-to-device. The AT&T agreement is not that.
Terminals, Not Phones
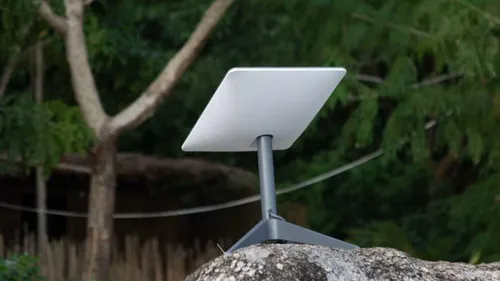
Amazon Leo, the constellation previously known as Project Kuiper, is a broadband system. Like Starlink’s core service, it connects to a dedicated terminal with its own antenna, installed at a site or on a vehicle. That terminal then provides connectivity to local equipment.
RCR Wireless highlighted this distinction in its coverage: the AT&T service is a satellite-to-terminal system for remote locations, field operations and vehicle backup, not a service that lets an ordinary smartphone talk to a satellite.
Why It Still Matters For IoT
For many industrial IoT deployments, a terminal is exactly what is needed. A mine site, a solar farm, an oil well pad or a construction compound often has dozens or hundreds of sensors, cameras and machines connected locally over Wi-Fi, private LTE or low-power networks. What those sites lack is a reliable path back to the cloud or head office. A satellite terminal provides that backhaul. We looked at how industrial sites connect their equipment in our explainer on industrial IoT and industrial connectivity.
Buying that link from the same operator that supplies the site’s fibre and cellular service simplifies procurement, support and failover. That convenience, rather than any new technology, is the main change the AT&T deal brings.
Where Amazon Leo Stands
Amazon’s constellation is still being built.
Satellites In Orbit
According to RCR Wireless, Amazon had deployed 392 Leo satellites by early September, with 315 in their operational orbits. Amazon holds regulatory approval for 3,232 satellites for its main broadband system and a further approval for 4,504 satellites to expand it. The company has been targeting commercial service in 2026.
Other Distribution Deals
AT&T is not Amazon’s only partner. Amazon Leo has also signed distribution agreements with Vodafone for Europe and Africa, DIRECTV in Latin America, NBN Co in Australia and Herotel in South Africa, as well as airlines including JetBlue and Delta. Working through established operators gives Amazon access to enterprise and consumer customers without building its own sales channels in every market.
The Starlink Gap
Amazon is chasing a well-established rival. SpaceX’s Starlink had about 12 million direct subscribers at the end of June and more than 11,000 satellites in orbit by late summer, according to RCR Wireless. Starlink’s connectivity business generated $4.3 billion in revenue in the second quarter. Amazon’s advantage lies elsewhere: its cloud business, its retail logistics and its existing relationships with enterprises that already run workloads on Amazon Web Services.
Amazon’s Direct-To-Device Plan
Separately from the broadband system, Amazon is building towards a network that connects phones and other cellular devices directly to satellites.
The Globalstar Acquisition
In April 2026, Amazon agreed to buy Globalstar, the satellite operator whose network powers emergency messaging on iPhones, in a deal worth more than $10 billion. Via Satellite reported that Amazon also reached an agreement with Apple to continue providing satellite services for current and future iPhone and Apple Watch models. The deal is expected to close in 2027.
Globalstar brings mobile satellite service spectrum, which is already licensed for satellite-to-device use. That makes it one of the most valuable assets in the direct-to-device market, where spectrum is often the hardest thing to obtain.
A Second Constellation
In June 2026, Amazon asked the US Federal Communications Commission for permission to launch up to 5,105 additional satellites for direct-to-device service. Broadband Breakfast reported that Amazon’s lawyers described the system as supporting “the leap from basic messaging to voice and data services.” Deployment is expected to begin in 2028.
If approved and built, that network would put Amazon in direct competition with SpaceX’s direct-to-cell service and with AST SpaceMobile, which works with AT&T and Verizon. We profiled AST’s approach in our story on the Texas startup betting on a cell tower in space.
Europe Wants Its Own Stake
The same week as the AT&T announcement, attention turned to Europe.
Operators Eye EU Spectrum
According to RCR Wireless, Deutsche Telekom, Orange, Telefónica and Vodafone are in early talks about a joint bid for the EU-controlled 2 GHz mobile satellite service band. The aim is to create a European-controlled direct-to-device service as an alternative to US providers. The effort is separate from IRIS², the EU’s own sovereign satellite programme.
The current 2 GHz licences in Europe expire in May 2027. In May 2026, the European Commission proposed reserving a third of the band for an EU operator serving government users, linked to IRIS², with the remaining two thirds for commercial services including direct-to-device and IoT.
Sovereignty And Leverage
Europe’s operators face an awkward position. Several already partner with US satellite providers: Deutsche Telekom works with SpaceX for direct-to-device services, and Vodafone has deals with both Amazon Leo and AST SpaceMobile. A European-controlled service would give them more bargaining power and address government concerns about depending on a small number of non-European companies for critical connectivity.
For IoT operators with European fleets and assets, this could eventually mean more choice of satellite coverage through the operators they already use. It is still early, and the talks may not lead to a joint bid.
The US Opens More Spectrum
Regulators are also moving. RCR Wireless reported that the FCC is pursuing more than 1,000 MHz of additional spectrum in the 12.7 GHz and 42 GHz bands, and is seeking comment on freeing up spectrum in the Ku-, Ka- and D-bands. The agency has also proposed more than 200 MHz for unlicensed satellite direct communication. Comments are due by 9 November, with replies by 7 December.
The unlicensed proposal is particularly relevant to IoT. Unlicensed spectrum has powered Wi-Fi, Bluetooth and LoRa-based networks on the ground. A dedicated unlicensed band for satellite links could open space to a wider range of device makers and service providers, though the rules, interference limits and power levels will decide what is actually possible.
The Spectrum Scramble
Behind all of these moves is a race for spectrum. Light Reading’s roundup of direct-to-device dealmaking this year lists SpaceX’s deals with EchoStar worth close to $20 billion, Amazon’s purchase of Globalstar, Rocket Lab’s agreement to buy Iridium for around $8 billion and the merger of Lynk and Omnispace to form Elveo Mobile. Viasat and Space42 are pooling their spectrum in a shared venture called Equatys.
Luke Pearce of CCS Insight summed up the shift in that report: “Direct-to-device has transformed MSS spectrum from a relatively niche asset into a scarce and strategically valuable foundation.”
What It Means For IoT
For companies running connected assets, the satellite market is changing in three ways.
Satellite Through Your Operator
First, satellite connectivity is increasingly sold by mobile operators rather than bought separately. AT&T’s deal with Amazon Leo is one example for terminals. Deutsche Telekom’s roaming agreement with Iridium for NB-IoT devices is another, at the low-power end. Over time, adding satellite coverage may become a line item on an existing contract rather than a separate procurement.
Two Kinds Of Satellite IoT
Second, buyers will need to distinguish between two very different services. Broadband terminals, such as those from Amazon Leo and Starlink, suit sites and vehicles that need high data rates and have power available. Direct-to-device and narrowband services suit small, battery-powered devices sending occasional messages, such as trackers and remote sensors. We explained the low-power side of this in our guide to the networks built to whisper. The right choice depends on data volumes, power budgets and cost, not on which service has the most satellites.
Timelines Still Uncertain
Third, many of the most ambitious plans are years away. Amazon’s direct-to-device network is not expected to begin deploying until 2028. The Globalstar deal will not close until 2027. Europe’s spectrum bid is at the discussion stage. AT&T’s Amazon Leo offering has no published pricing. Plans built around future services need contingencies.
Questions For Buyers
For enterprises weighing satellite options, a few questions can help cut through the announcements.
What do the assets actually need? A remote site with cameras and dozens of sensors needs broadband backhaul. A tracker on a trailer needs a few bytes a day.
Which satellite partners does your current operator work with, and can satellite be added to existing contracts? Managed offerings may cost more but reduce integration work.
What happens at the boundary between networks? Failover between fibre, cellular and satellite should be tested, not assumed.
What is the real availability date and price? Several services announced this year are not yet commercially available.
How locked in will you be? Terminals, SIM arrangements and platform integrations can make switching providers expensive later.
A Market Being Rewired
The AT&T and Amazon deal is not the most technically dramatic announcement of the month. It does not connect phones to satellites or introduce new standards. What it does show is the direction of the market: satellite capacity is becoming another layer that operators package and sell, alongside fibre and mobile.
Around that, Amazon is buying spectrum and planning a direct-to-device constellation, Europe’s operators are looking for a stake of their own and regulators are opening new bands. For the IoT industry, the result should be more ways to keep assets connected beyond terrestrial coverage. How quickly those options arrive, and at what price, will become clearer as the plans move from announcements to service.